
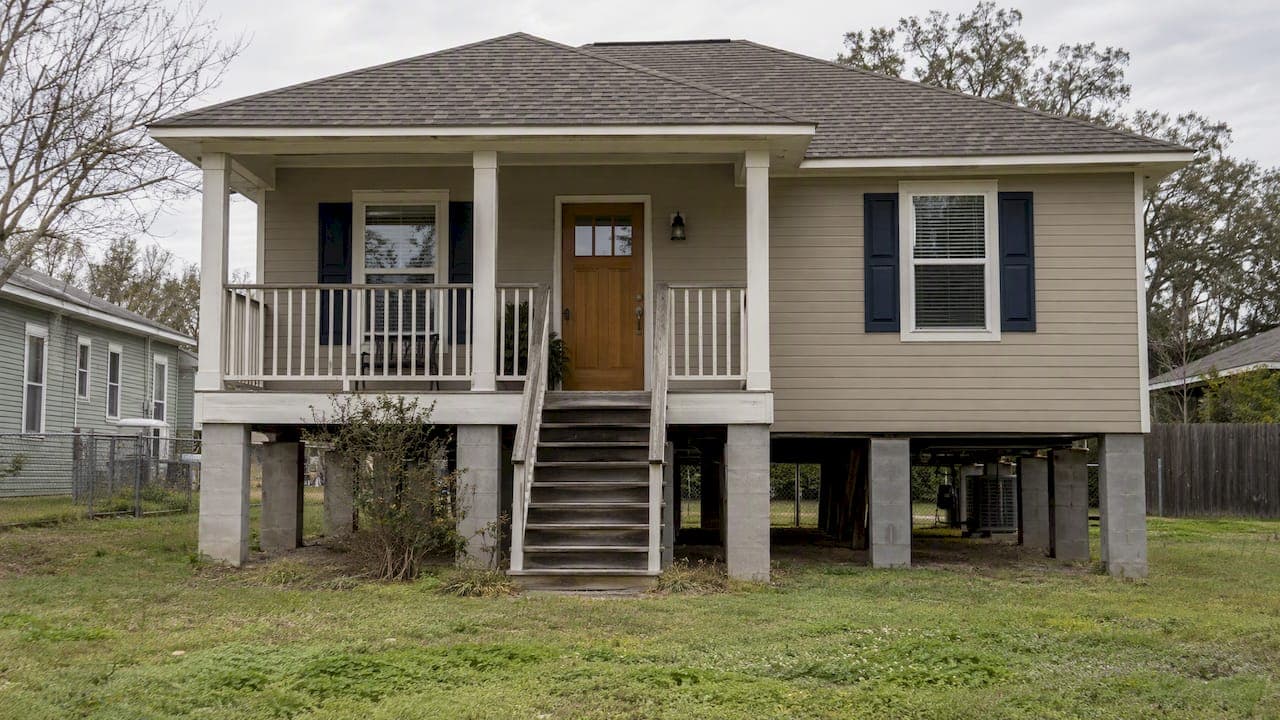
Risk Rating 2.0 in Louisiana: Why the 18% Cap Is Only Part of It

Risk Rating 2.0 changes how FEMA prices flood insurance for every Louisiana policyholder, and most homeowners will see only modest monthly shifts rather than dramatic spikes. A statutory 18% annual cap softens the transition on most primary residences, so the real urgency right now is simpler: call your agent and confirm your Elevation Certificate is accurate before your next renewal.
TL;DR:
- Federal law caps annual increases at 18% for most primary residences, though homes with repeated claims or high rebuilding costs may rise over several renewals.
- FEMA says roughly two thirds of Louisiana policyholders with older homes may see decreases; nationally, 97% see monthly changes of $20 or less.
- Louisiana’s resolution and court challenge have not paused FEMA’s rules, so renewals still use Risk Rating 2.0 while lawmakers seek changes.
Table of Contents
- What Is Risk Rating 2.0 and How Is It Different From the Old System
- How Risk Rating 2.0 Changes Premiums in Louisiana
- Louisiana’s Response: House Resolution No. 291 and the Court Challenge
- What Louisiana Homeowners Can Do Now to Manage Their Rating
- Why a Local Agent Matters More Under Risk Rating 2.0
- A Louisiana Agent’s Take on What Matters Most Right Now
- Get Your Flood Policy Reviewed Before Your Next Renewal
- FAQ
- Sources
What Is Risk Rating 2.0 and How Is It Different From the Old System
For decades, the National Flood Insurance Program priced policies mostly by flood zone and base flood elevation, a blunt method that charged similar rates to very different homes sitting in the same zone. Risk Rating 2.0 throws that approach out and prices each property individually.
FEMA’s technical fact sheet lays out the structure-specific factors now driving your premium, including elevation, distance to water, flood frequency across multiple flood types, and the rebuilding cost of your home. The rollout happened in two phases: new policies written on or after October 1, 2021 were priced under the new model, and every renewing policy moved to Risk Rating 2.0 by April 1, 2023.
FEMA states its goals plainly: get the program on sound actuarial footing and make premiums reflect each property’s actual flood risk, not just its zip code. In practice, that means two homes across the street from each other can now carry very different premiums based on real differences in elevation and construction.
- Elevation relative to base flood elevation now carries significant weight in your rate.
- Distance to a coast, river, or other flood source factors directly into the calculation.
- Multiple flood types, not just riverine or coastal surge, are modeled together.
- Replacement cost of your home replaces the old flat coverage-amount assumptions.
How Risk Rating 2.0 Changes Premiums in Louisiana
Louisiana’s flood exposure is unlike almost anywhere else in the country, and FEMA’s own state-level data confirms that Risk Rating 2.0 is not a uniform rate hike here. According to FEMA’s Louisiana state profile, roughly two-thirds of policyholders with older, pre-FIRM homes may actually see their premiums decrease under the new model, because those homes are now rated on their real elevation and construction rather than a broad zone assumption.
Most Louisiana policyholders will see changes of $20 or less per month. FEMA reports that 97% of policyholders nationally fall into this range, meaning the headline fear of runaway premium increases does not match what most households actually experience at renewal.
That does not mean every policy stays flat. Here is what actually determines which direction your premium moves:
- Homes built above base flood elevation, with modern construction, tend to see rates hold steady or drop.
- Homes with a documented history of repeated claims tend to move toward a higher full-risk rate.
- Higher replacement-cost homes, since rebuilding cost is now a direct input, often carry higher premiums than older ratings reflected.
- Properties still transitioning toward their full-risk rate are protected by law from sudden jumps.
For most primary residences, federal law caps the annual increase at 18% per year, which means a home moving toward a much higher full-risk premium does so gradually over several renewal cycles rather than in one shock. Repetitive-loss properties and high-value homes are the ones most likely to feel the full weight of that glidepath over time, which is exactly why documentation and mitigation matter more now than they did under the old zone system.
Louisiana’s Response: House Resolution No. 291 and the Court Challenge
Louisiana lawmakers have not stayed quiet on this. During the 2025 Regular Session, the Legislature adopted House Resolution No. 291, formally memorializing Congress to address what the state sees as flaws in how Risk Rating 2.0 was rolled out.
- The resolution asks Congress to support the Flood Insurance Affordability Act to ease the burden on coastal parishes.
- It also calls for a transparency act so FEMA has to show its rating methodology more clearly to policyholders and lawmakers.
- At its core, the resolution asks Congress to pause, reform, or end Risk Rating 2.0 until those concerns are addressed.
Separately, a legal challenge played out in federal court. In Louisiana v. Mayorkas, the Eastern District of Louisiana denied a preliminary injunction that would have blocked Risk Rating 2.0, while allowing certain plaintiffs to continue pursuing their claims on narrower standing grounds.
What does this mean for you right now? Neither the resolution nor the litigation has paused FEMA’s current rating methodology or delayed renewals. Your policy renews under Risk Rating 2.0 regardless of how these efforts eventually resolve, so planning around today’s rules, not a hoped-for reversal, protects you better.
What Louisiana Homeowners Can Do Now to Manage Their Rating
The single biggest lever most homeowners overlook is also the simplest: make sure FEMA and your insurer have accurate, current information about your home. Since Risk Rating 2.0 prices your specific structure, outdated or missing paperwork can cost you money you never needed to pay.
- Order or update your Elevation Certificate if yours is outdated or was never filed, since elevation is now a direct rating input.
- Document any mitigation already in place, like compliant flood openings or elevated mechanical equipment, and send that paperwork to your agent.
- Ask your agent to review whether your home qualifies for Community Rating System discounts tied to your parish’s floodplain management participation, which FEMA notes can average meaningful savings for eligible communities.
- Look into Hazard Mitigation Assistance grants through your parish emergency management office if elevation or floodproofing work is a realistic long-term project for your home.
- Mark your renewal date now and schedule a policy review at least sixty days ahead, so there is time to gather documentation before the rate locks in.
Quick wins, like submitting an updated Elevation Certificate or proof of flood vents, often show up in your next renewal. Elevating a structure or raising mechanical systems is a longer-term project, but it directly lowers the inputs FEMA uses to calculate your full-risk rate.
Pro Tip: Keep a folder, physical or digital, with your Elevation Certificate, photos of flood openings, and any mitigation receipts. Handing that folder to your agent at renewal time is often faster than waiting on FEMA’s own records request process.

Why a Local Agent Matters More Under Risk Rating 2.0
A rating system this detailed rewards accuracy, and accuracy is exactly where a local agent earns their place in your corner. We audit your policy against your actual home, not a generic template, which means catching an outdated Elevation Certificate or a missing mitigation record before it costs you at renewal.
- We verify or order Elevation Certificates and walk you through what the numbers mean for your rate.
- We submit mitigation documentation directly so it is reflected in your next renewal cycle.
- We explain where NFIP coverage fits against private flood market options, since Louisiana homeowners increasingly have both to choose from.
- We provide bilingual claims support, because filing a claim should never be harder than it already is.
- Our team responds directly in disaster zones, so you are not stuck on hold with a call center after a storm.
Steve Root has spent more than 20 years building this agency in Baton Rouge, and our 356 five-star Google reviews reflect what happens when a local team actually shows up. If you are unsure whether your current policy reflects your home’s real risk, schedule a review before your next renewal date.
A Louisiana Agent’s Take on What Matters Most Right Now
I have watched Risk Rating 2.0 play out across hundreds of Louisiana policies, and the pattern is consistent: the homeowners who come out ahead are the ones who documented their homes accurately, not the ones who chased the cheapest quote. Louisiana sits in the bullseye for hurricanes, and a policy built on outdated paperwork will cost you far more than $20 a month if it fails you when water is in your living room. Protect the coverage first. If you are not sure where your policy stands, get a review.
— Steve Root
Get Your Flood Policy Reviewed Before Your Next Renewal
We built our flood insurance practice around the paperwork details that actually move your Risk Rating 2.0 premium: accurate Elevation Certificates, documented mitigation, and a clear read on whether NFIP or private flood coverage fits your home best.
Our team reviews your current policy against your home’s real risk profile, submits documentation on your behalf, and stays local when a storm hits so you are never managing a claim alone. Visit our flood insurance page to schedule a policy review with a Baton Rouge based agent who answers the phone.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What does Risk Rating 2.0 mean for flood insurance?
Risk Rating 2.0 means your flood insurance premium is now based on your specific property’s elevation, distance to water, flood history, and rebuilding cost rather than a broad flood zone designation. For most Louisiana policyholders, FEMA reports changes of $20 or less per month, with many older homes actually seeing decreases.
Who has the cheapest flood insurance in Louisiana?
Flood insurance pricing now depends on your home’s elevation, construction, and claims history rather than a single statewide rate, so there is no flat answer for who pays least. Homes built above base flood elevation with documented mitigation features generally see lower premiums under Risk Rating 2.0 regardless of parish.
What are the worst flood zone codes to be in?
Zones like VE and AE, which indicate high-velocity coastal surge or base floodplain risk, historically carried the highest base rates under the old zone system. Under Risk Rating 2.0, your zone still matters as one input, but your home’s actual elevation and construction now carry more weight in the final premium than the zone code alone.
What are the flood zones in Louisiana?
Louisiana includes a mix of high-risk zones such as A, AE, and VE along coastal and riverine areas, moderate-risk zones like X with shading, and minimal-risk zone X in higher inland areas. Your specific zone is listed on your flood insurance policy and FEMA’s flood maps, and it remains one factor among several under Risk Rating 2.0.
How do I appeal my Risk Rating 2.0 premium in Louisiana?
There is no formal appeal process for the rating methodology itself, but you can request a review if you believe your Elevation Certificate, square footage, or other property details are inaccurate. Submitting updated documentation to your agent is the most direct way to correct a premium that does not reflect your home’s actual condition.
Sources
- Risk Rating 2.0 (FEMA technical fact sheet, April 2025)
- HLS 25RS-3661 ORIGINAL 2025 Regular Session HOUSE RESOLUTION NO. 291
- Louisiana v. Mayorkas — federal district court opinion and docket